Record revenue. Record EBITDA.
Still a £43m loss.
Manchester United's FY2026 operations produced a record £216.4m of adjusted EBITDA and a £22.6m operating profit. Net finance costs of £69.6m turned that into a £43.0m net loss.
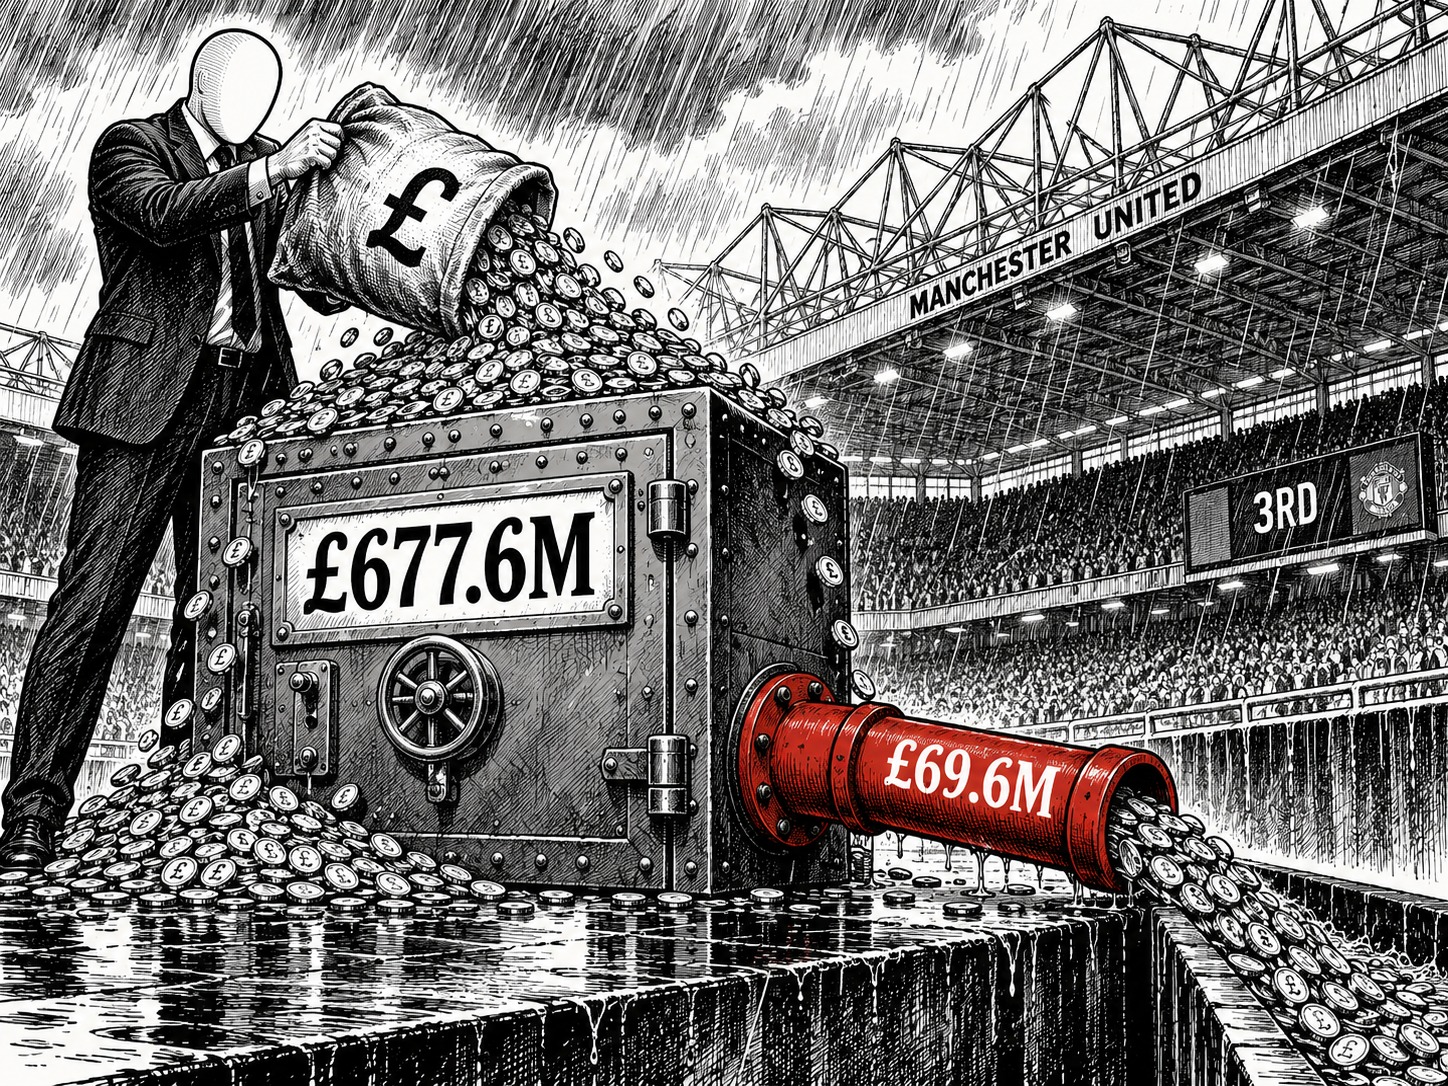
Manchester United reported record revenue of £677.6m for the year to 30 June 2026, without playing a single UEFA match. Adjusted EBITDA reached a record £216.4m, up 18.4%. After amortisation, depreciation, player sales and exceptional items, the club made an operating profit of £22.6m, against an operating loss of £18.4m the year before. The football business made money. The cost of carrying the club's debts took it back. Net finance costs were £69.6m, more than three times operating profit and up from £21.2m. The largest element, £35.6m, is interest on the senior secured notes, term loan and revolving facility; the notes and term loan descend, through successive refinancings, from the 2005 acquisition debt. The second, £18.9m, is the unwinding of discount on transfer fees still owed to other clubs, the cost of buying players on instalments. The third, £10.0m, is an unrealised currency loss on dollar borrowings that are not hedged. Strip out the currency loss entirely and finance costs are still £59.6m, more than two and a half times operating profit. The direction from here is not lower. In June 2026 the club replaced $425m of notes at 3.79% with $550m of notes at 5.36%, and guided FY2027 adjusted EBITDA to £205m to £225m, below this year's record.
Methodology note. All figures are taken from the reconciliation of loss for the period to adjusted EBITDA (supplemental note 2) in Manchester United's fourth quarter and full year fiscal 2026 results, filed on Form 6-K on 23 September 2026, and from Note 9 (net finance costs) of the Form 20-F for the year ended 30 June 2026. Bars are drawn from unrounded figures in £ thousands; labels are rounded to £0.1m. Adjusted EBITDA is a non-IFRS measure defined by the club. The £35.6m interest figure is interest payable on the secured term loan facility, senior secured notes and revolving facilities. "Other costs, net of finance income" (£5.2m) is the residual of net finance costs after the three named items; it includes amortisation of issue costs, hedge ineffectiveness, costs of transfer receivable transactions, bank and lease interest, less finance income. The foreign exchange loss is unrealised; the prior year included an unrealised gain of £22.9m. The "£59.6m" figure is net finance costs less the £10.0m foreign exchange loss. The FY2027 guidance is the club's own forward-looking statement. The interest on the notes is paid to lenders, not to shareholders; this piece makes no claim about who receives finance costs beyond the filings.